
Starbucks’ latest results show how a shift to licensing changes reported revenue—and why investors and operators need separate measures of demand and economics.
The reporting change behind the headline
In results announced on 29 October 2026 for the quarter ended 27 September, Starbucks reported global comparable coffeehouse sales growth of 7.2%, while consolidated revenue fell 4% to US$9.1 billion. The company attributed the revenue decline primarily to converting its China retail operations to a licensed joint venture.
The International segment makes the distinction clearer: revenue fell 37% to US$1.3 billion. Starbucks said the conversion, completed in its third fiscal quarter, reduced company-operated revenue while contributing to higher product sales and royalty revenue from licensees. These are reported results, not a newly announced transaction.
Comparable sales are not a whole-network measure
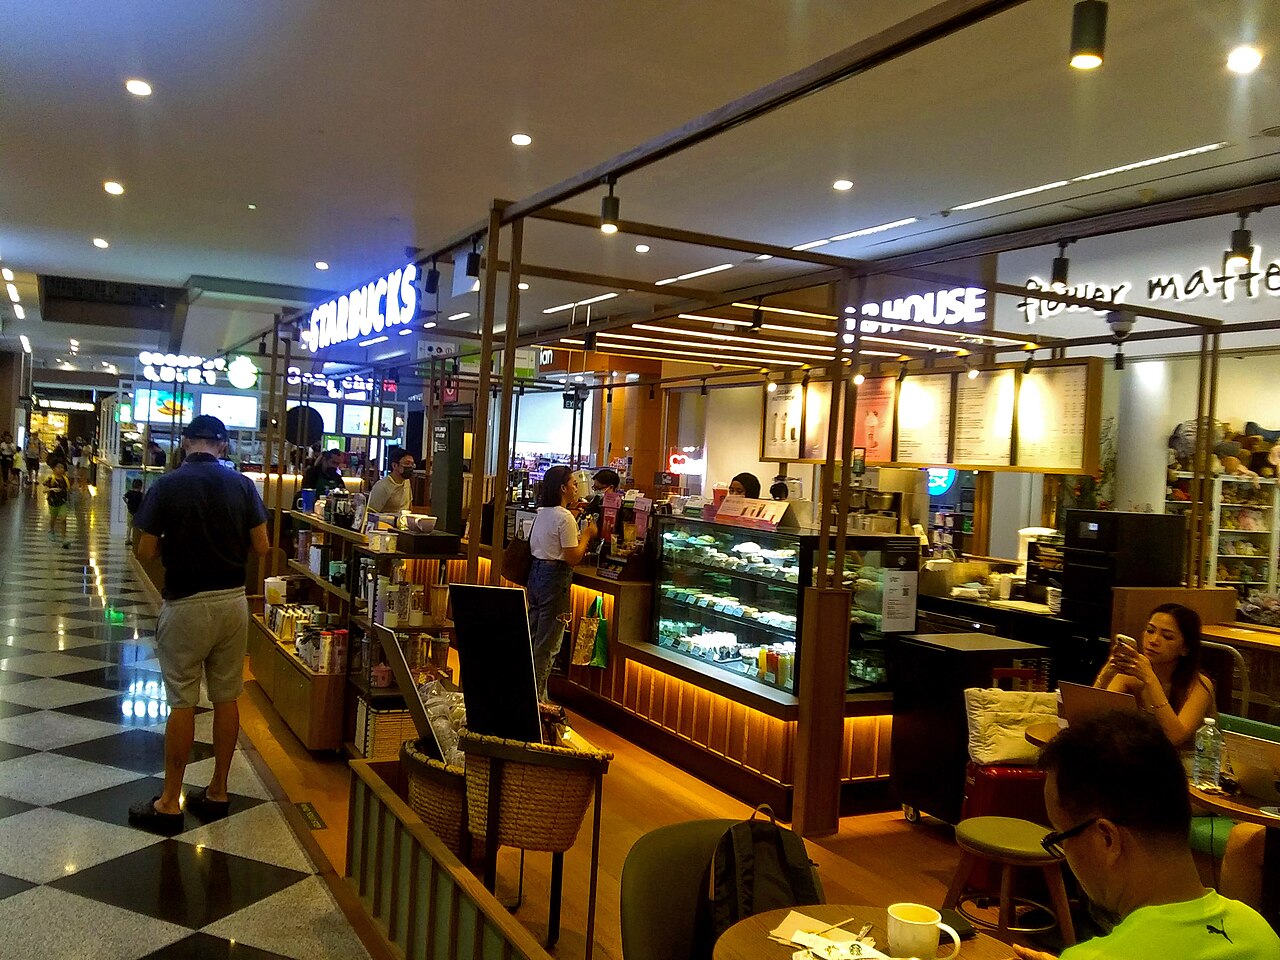
Starbucks ended the quarter with 41,607 coffeehouses, 68% licensed. Its comparable-sales definition covers company-operated coffeehouses open at least 13 months, with stated exclusions. International comparable sales rose 0.9%, combining a 3.7% increase in average ticket with a 2.8% fall in transactions. Those figures should not be read as the performance of every licensed store.
Source: Starbucks’ Q4 and full fiscal year 2026 results, published 29 October 2026.
What investors should separate
The following is Star Brands Consulting Group’s commercial analysis of the disclosed results.
A change in operating model changes what enters the brand owner’s revenue line. Retail takings at a directly operated store and receipts from supplying or licensing a partner represent different activities. Comparing the two periods without identifying that change can confuse a smaller reporting base with a smaller customer business.
A useful assessment therefore separates three questions: what consumers bought, what the brand owner recognised as revenue, and what cash the operating partner retained after its obligations. Stronger results on one measure do not establish improvement on the others. A licensing transition also requires attention to the costs and capital commitments retained by each party.
For an investor evaluating an international brand, the practical request is a reconciliation of continuing operations, transferred operations and recurring partner income. Comparable-sales coverage, ownership changes and reporting periods should be explicit before drawing conclusions from growth percentages.
What prospective operators should test
For an operator assessing a licensing opportunity, a brand’s consolidated results are context rather than a substitute for local unit economics. The investment case needs evidence on customer traffic, achievable ticket, occupancy, labour, sourcing and the contractual payments that the operator would actually bear.
Partner qualification should also test working capital, management depth and the ability to maintain service standards across a territory. Development commitments need to be assessed against site availability and the capacity to train and supervise teams. A large international footprint does not establish that rights are available in a particular market.
The same discipline applies to performance reporting after launch: distinguish customer transactions from ticket growth, new openings from mature stores, and sales from cash generation. Contractual reporting and audit arrangements should make those distinctions visible to both the brand owner and the operator.
Implications for brand owners
A licensing strategy should specify how commercial control will work after operating responsibilities change. Brand standards, product supply, data access and corrective action need clear ownership. Otherwise, the financial reporting may become lighter while the work of protecting the customer experience remains unresolved.
For brands and operators comparing direct entry, licensing and partnership structures, Star Brands Consulting Group’s Market Entry Advisory supports assessment of entry routes, partner requirements and execution readiness.
Leave a Reply