Kane Biotech’s non-exclusive Canadian distribution agreement with The Stevens Company shows why regulated market access is not simply a question of territory. The commercial test is whether a manufacturer and distributor can turn licences, logistics and institutional relationships into procurement, adoption and repeat orders.
What Kane Biotech and Stevens signed
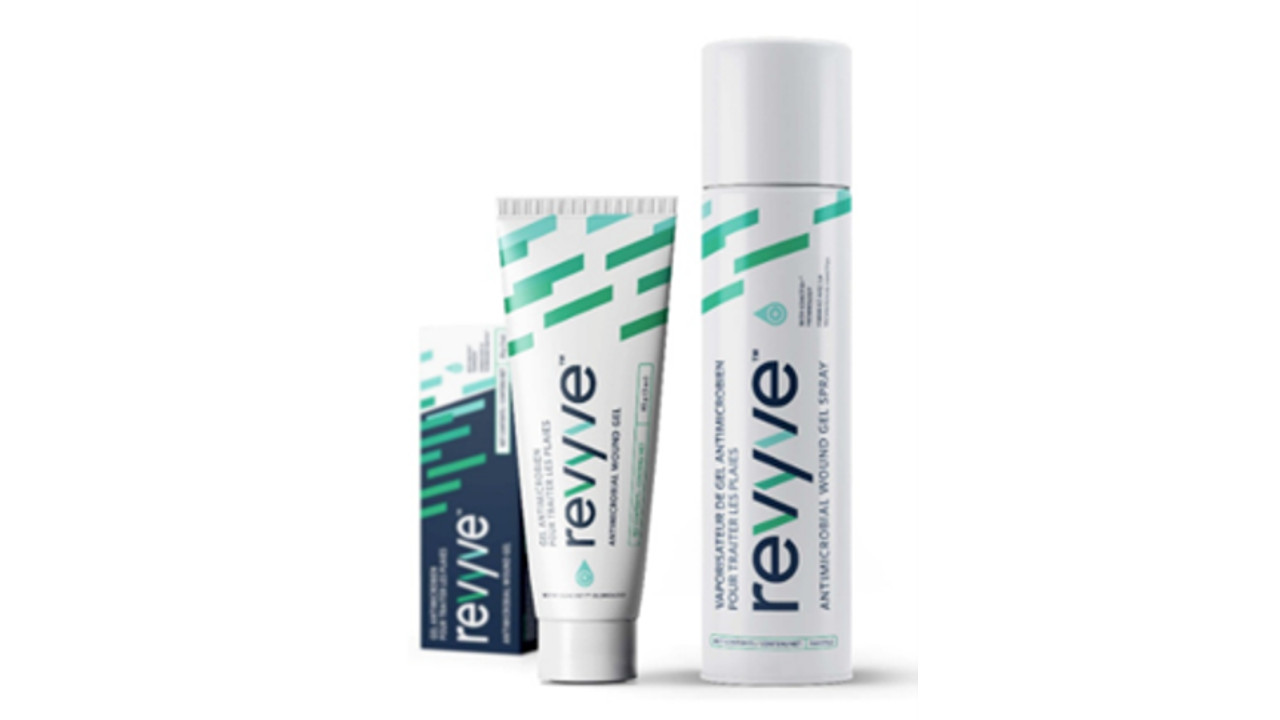
Kane Biotech announced the agreement on 20 October 2026, but said it became effective on 1 October. Under the non-exclusive arrangement, Stevens will distribute revyve Antimicrobial Wound Gel in one-ounce and three-ounce formats, plus a five-ounce Gel Spray, across Canada.
The announcement says the products are licensed by Health Canada and that Stevens serves hospitals, long-term-care facilities and community healthcare providers. It does not disclose financial terms, minimum purchases, sales targets, inventory commitments or expected revenue. Nor does nationwide coverage mean that every institution has listed, purchased or adopted the products.
Non-exclusive does not mean commercially weak
Exclusivity can concentrate a distributor’s attention, but it also transfers leverage and execution risk. A non-exclusive agreement preserves more optionality for the manufacturer: Kane can potentially add channels or partners without first unwinding a countrywide grant. The trade-off is that Stevens may have less contractual reason to prioritise revyve over other products unless economics, training and customer demand support the effort.
That is an inference from the contract structure, not a disclosed term of this agreement. The practical point for brand owners is that territorial language should be assessed alongside account coverage, launch resources, competing lines, service levels and performance reporting.
Why distributor infrastructure matters
Stevens describes itself as a national Canadian healthcare distributor representing more than 500 manufacturers through sales, customer-service and distribution infrastructure. Its company history traces the business to 1830 in the United Kingdom and 1874 in Canada.
The Kane announcement also points to Stevens’ recent expansion through Schaan Healthcare Products in Saskatchewan, CB Medical in Alberta and the integration of TRH Services. That acquisition-built footprint may strengthen regional access, but infrastructure alone does not create demand. Each added product still needs compliant claims, internal onboarding, inventory planning, sales-team understanding and a workable route through institutional procurement.
The real work begins after appointment
For regulated products, a distributor agreement is better viewed as an operating framework than as proof of commercial traction. The post-signing work should include:
- Account mapping: identify which hospitals, long-term-care groups and community providers fit the product and who controls evaluation and purchasing.
- Commercial onboarding: confirm product data, pricing architecture, inventory locations, lead times, returns and customer-service ownership.
- Training and claims control: ensure sales materials and field conversations remain within authorised product claims.
- Demand and inventory discipline: separate initial stocking from genuine sell-through and track reorder behaviour.
- Performance visibility: agree on reporting that shows qualified opportunities, conversion, inventory ageing and regional coverage.
What investors, brand owners and distributors should test
Investors should avoid treating the agreement as a revenue forecast. Kane’s own announcement includes the usual forward-looking cautions around market acceptance, regulatory requirements, financing and dependence on commercial partners. Useful evidence will come later: product onboarding, qualified institutional demand, repeat purchasing and the relationship between channel expansion and working capital.
Brand owners evaluating a national distributor should test more than warehouse locations. They should examine customer access by province, specialist sales capability, competing portfolios, quality systems, recall procedures and the data available to manage the relationship. Distributors, in turn, should test regulatory status, margin after service costs, expected sales-cycle length, training burden and the manufacturer’s ability to maintain supply.
The broader lesson is that distribution rights create access options, not outcomes. Non-exclusive structures can be sensible when a brand needs flexibility, but they require sharper operating governance because neither party can rely on territorial lock-in to substitute for execution.
Sources
- Kane Biotech: distribution agreement announcement, 20 October 2026
- The Stevens Company: national distribution overview
- The Stevens Company: corporate history
- Kane Biotech: Canadian product information
Star Brands Consulting Group helps companies assess distributor structures, partner fit and route-to-market execution through its Market Entry Advisory.
Leave a Reply