
Carrefour’s proposed purchase of Codifrance highlights the value of wholesale reach—and the retailer relationships needed to sustain it.
What Carrefour announced
On 19 October 2026, Carrefour announced an agreement with Colruyt Group to acquire Codifrance at an enterprise value of €152 million. Codifrance supplies approximately 3,100 customers in France, operates three distribution centres and employs nearly 380 people. Its sales were €307 million in the 2025/26 financial year.
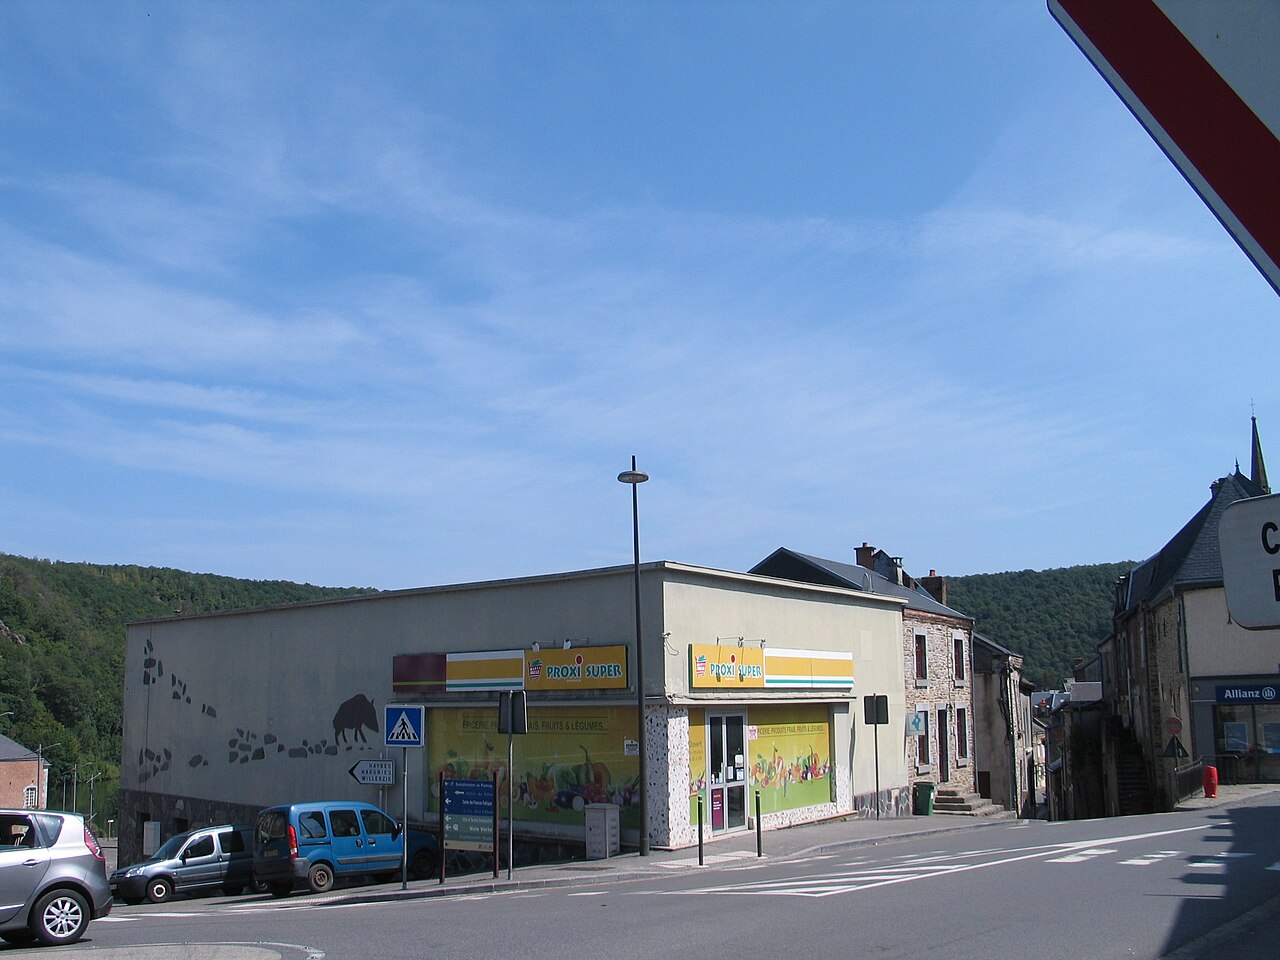
The company announcement places the transaction within Carrefour’s convenience retail strategy. Carrefour already supports independent retailers through Proxi, which has more than 1,500 stores. Completion remains conditional on French Competition Authority approval and other customary conditions; Carrefour expects closing in the first half of 2027.
Distribution reach requires retailer retention
Star Brands analysis: A wholesaler’s customer count should not be treated as a count of stores the buyer will own. The commercial value of a distribution platform depends on the orders its customers continue placing after a change of control.
For an investor evaluating this kind of acquisition, the key diligence questions concern customer concentration, purchasing frequency, contract duration and renewal behaviour. A large account base can conceal dependence on a smaller group of high-volume customers. The strength of the business therefore needs to be tested through trading records and contract terms, rather than inferred from network size.
Integration is a service test
Independent retailers have practical reasons to remain with a distributor: dependable deliveries, suitable pack sizes, competitive purchasing terms and an assortment that fits local demand. An integration plan should protect those services while examining potential purchasing and logistics efficiencies.
Warehouse consolidation, range changes or new order systems may look attractive in a financial model. Each also needs an operational test: can the retailer still obtain the products it needs, in the quantities it can sell, at the time it needs them? Savings that weaken availability or cause customers to switch suppliers can undermine the acquisition case.
What operators and brand owners should examine
Retail operators assessing a supplier transition should establish who will manage their account, whether ordering and delivery arrangements will change, and what their existing agreement permits. They should distinguish announced intentions from binding changes to commercial terms.
Brand owners should assess how a distributor’s changing ownership might affect range reviews, promotional planning and access to independent outlets. A customer network is a route-to-market capability; it does not guarantee a listing for any particular product.
For investors, enterprise value alone does not establish affordability or expected returns. A useful assessment would also require profitability, working-capital needs, customer retention and integration costs. Carrefour’s announcement does not provide enough information to calculate those returns.
These are analytical diligence considerations, not disclosed integration commitments or forecasts for Codifrance. Until completion, operators should continue to work from their current contractual arrangements and confirmed communications.
Source and advisory contact
Primary source: Carrefour regulatory announcement, 19 October 2026.
For support assessing distribution partners or a market-entry strategy, contact Star Brands Consulting Group.
Leave a Reply